

Last September, I wrote that Europe’s telcos held one ace no CTV platform could copy: the monthly bill. Broadband, mobile, Netflix and DAZN on a single invoice.
A year on, that ace is still a massive advantage for telcos and on Friday I bet every TV maker in the business walks into Messe Berlin for IFA to show us a brighter panel or their latest AI integration. These features matter to sell TVs (and hopefully AI brings relief to the content discovery headache we face as users every night) but does that do enough to become (and stay) the default entertainment hubs? I have my doubts as evidenced by the scoreboard I built earlier this summer to grade who was best placed to be THE super aggregator in Entertainment. Let’s dig in.
Today at a glance:
Everyone wants to own the front door
But who builds the till
Before AI assistants become subscription managers
Everyone owns the front door
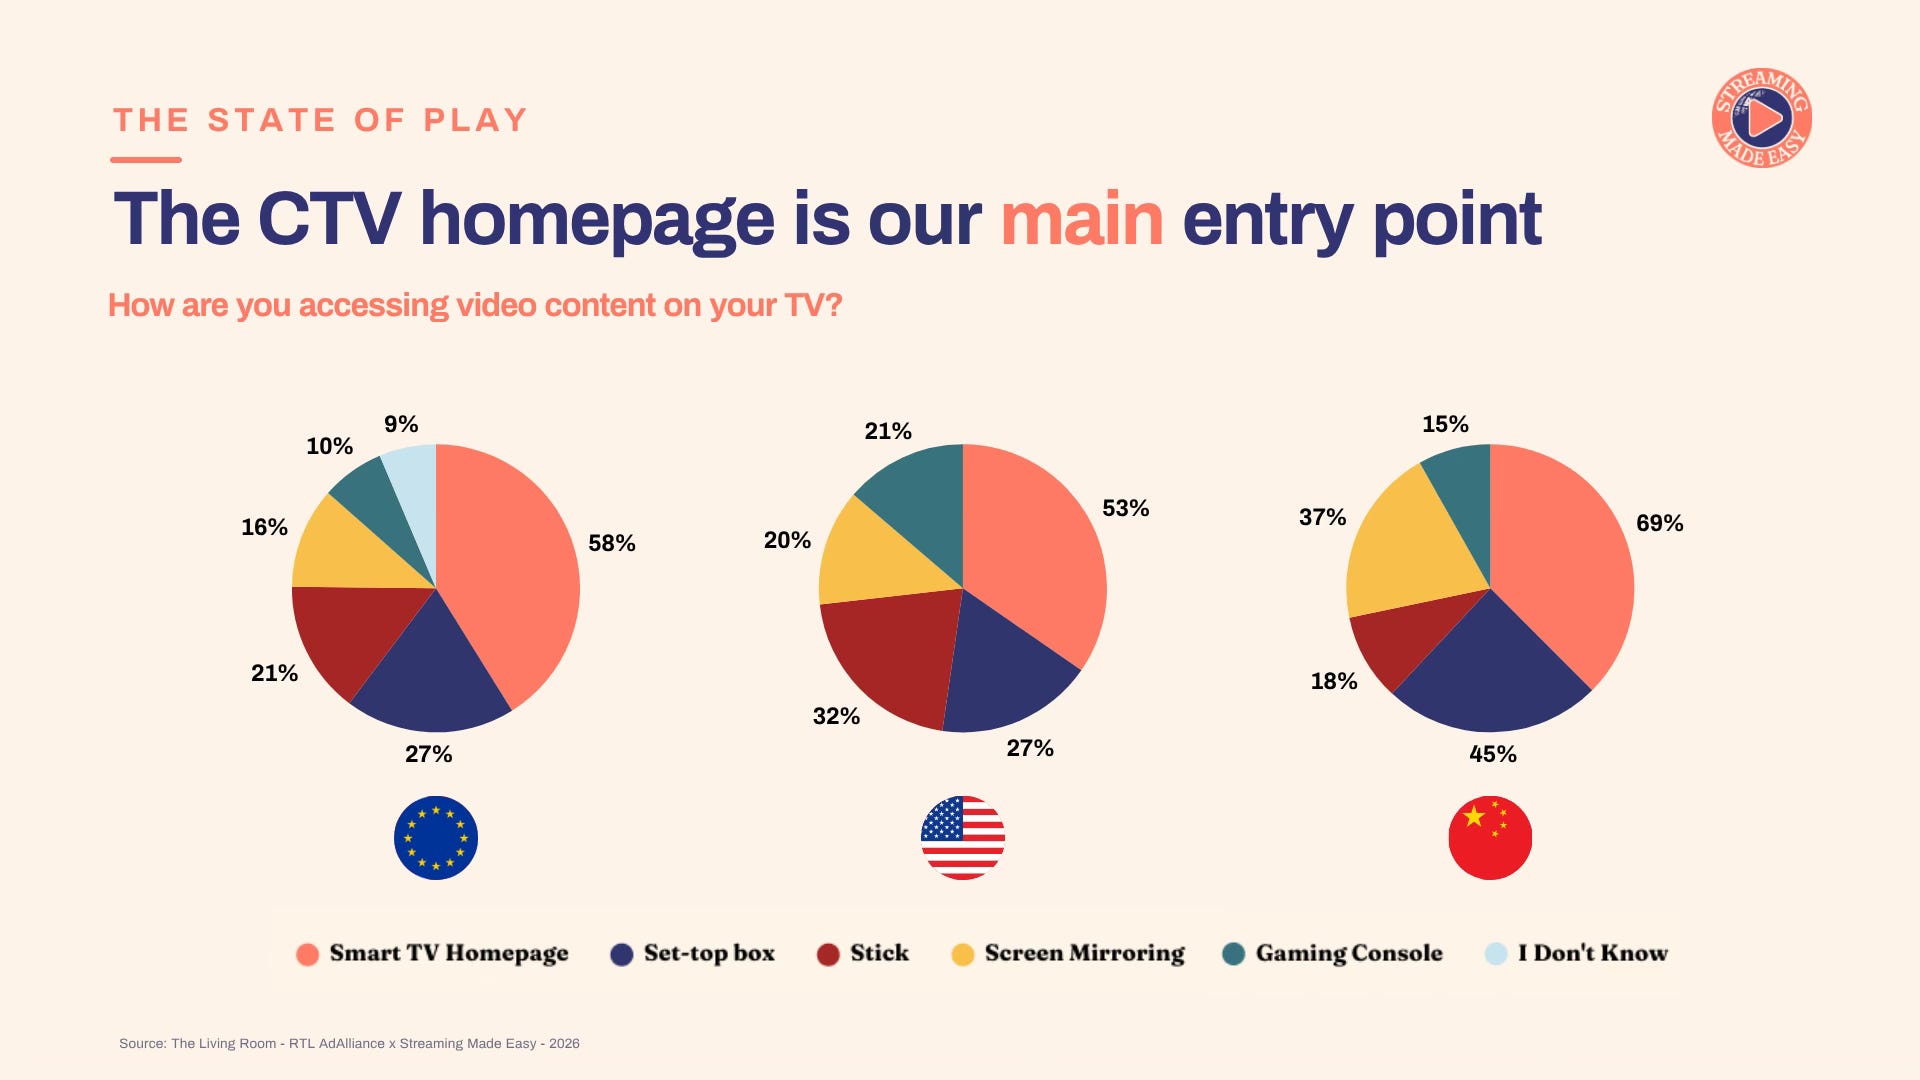
The growing importance of the CTV homepage as an entry point to entertainment is undeniable (pushing Telcos to seek distribution of their apps on CTV). In the 2026 Living Room Study we ran with RTL AdAlliance, 58% of Europeans say the smart TV homepage is how they get to video on the TV set; 53% in the US (surprisingly low number but I guess makes sense with sticks added to the mix) and 69% in China.
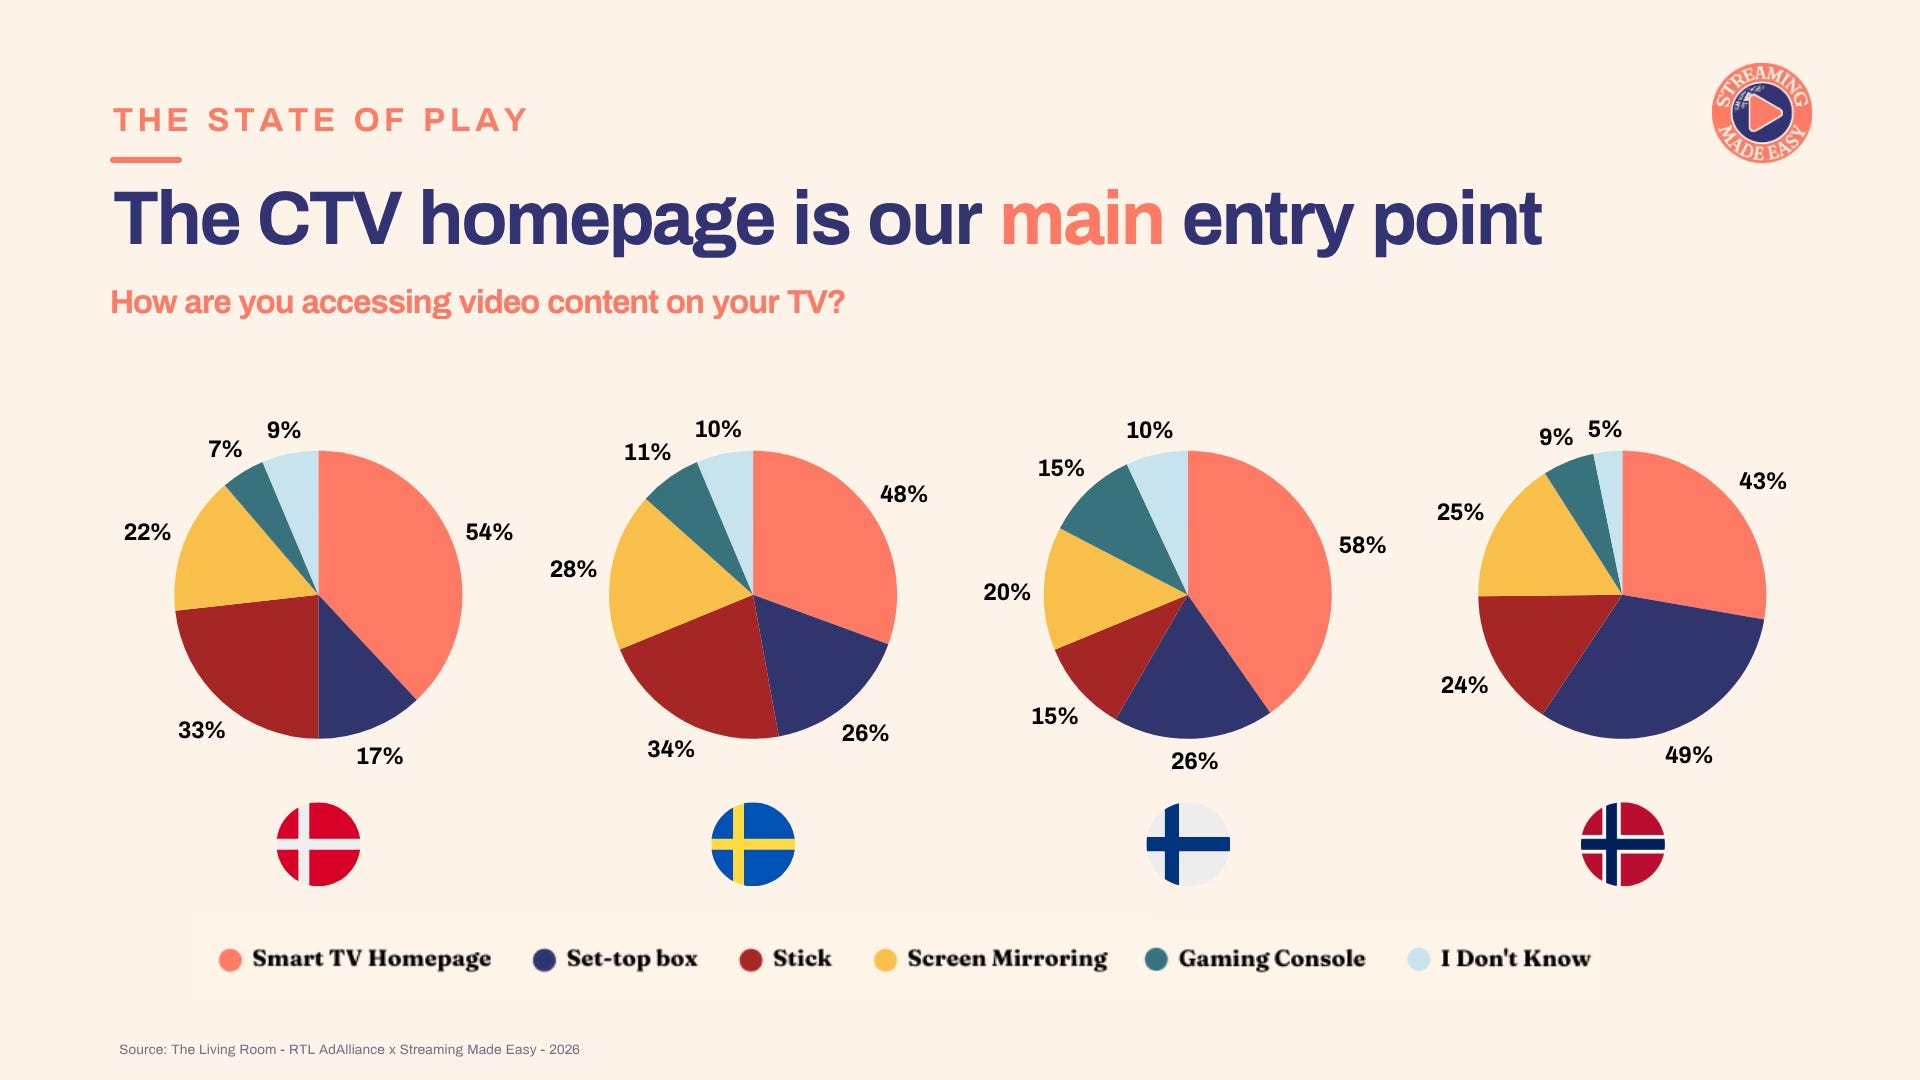
In the Nordics (where I was last week for the Copenhagen TV Festival), the trend holds (except in Norway where set top boxes lead).
But who’s grabbing that subscriber money past the CTV homepage?
Only two player types score full marks in my score card.