

Who stands between your service and the Dutch viewer? 5 graphs to find out, the second edition of our 5-graph series following our inaugural Germany edition. Each one points to a move if you sell, buy or distribute video there.
My one-line read: Dutch viewing is spread across many services and a few companies control the way to the screen.
You’ll get the share of Dutch households paying for 4 or more streaming services, the one age group where Netflix edges YouTube, how fast the 2 companies serving most Dutch households are losing share and the 3 TV makers sitting between your service and the screen.
The numbers come from NMO’s Media Trends 2025 and Screenforce’s Trends in Digital Media 2026.
Second place is Dutch
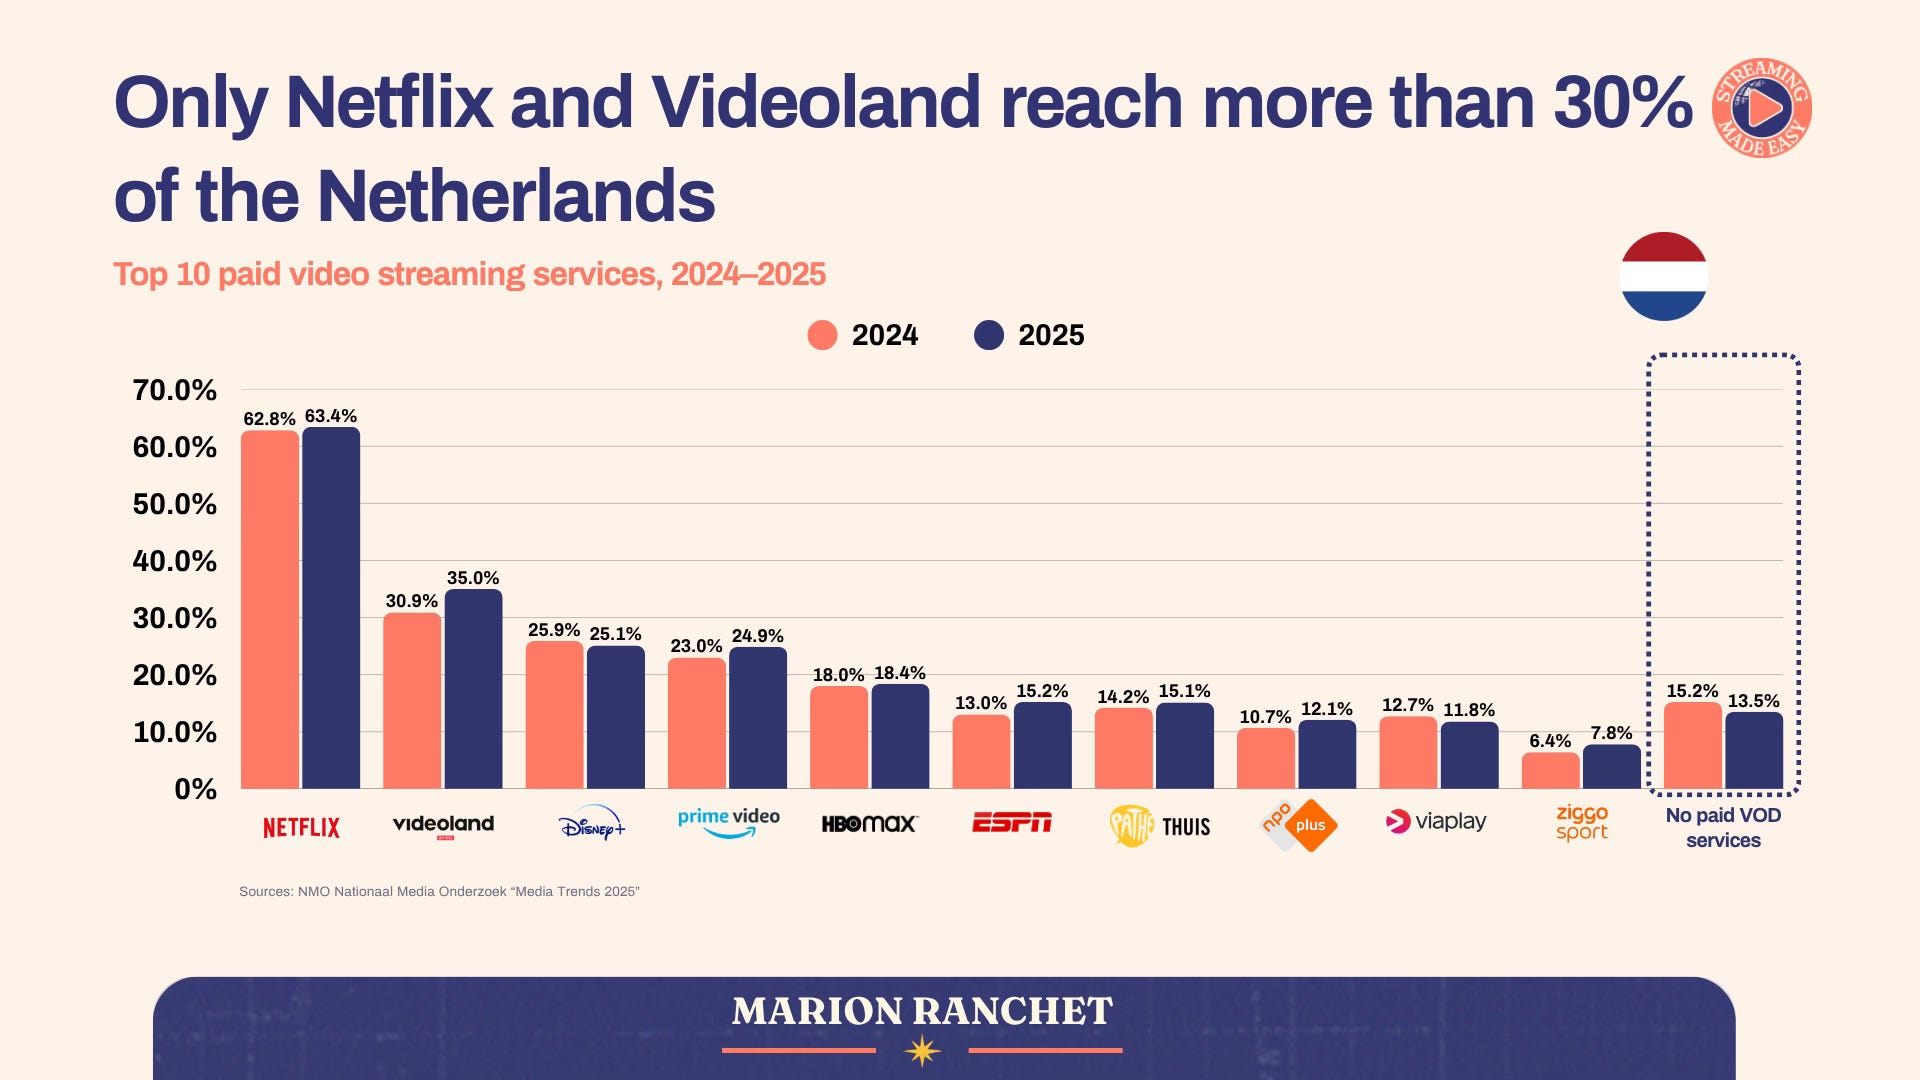
When local relevance beats global catalogues. NMO has Videoland about 10 points clear of both Disney+ and Prime Video, after a 4.1-point gain in a year while Disney+ lost 0.8 and Netflix only gained 0.8.
Netflix is the anchor and Videoland is the second pillar, since everything else tops out at 25.1%. If you buy or sell paid streaming reach in the Netherlands, plan around those two first.
With the Viaplay’s acquisition now cleared, DPG Media (owner of Videoland, bought from RTL Netherlands in 2025) will strengthen its 2nd spot with a combined reach of up to 46.8% (assuming there’s little overlap between the two). The two services are said to stay separate for now. Come 2027 the Videoland team will work on a stand alone sports offer based on the Viaplay assets (does that mean Videoland vs Videoland Sports?). I’m not sure about two separate offerings, one brand with an entertainment + sports tier plus a sports tier only would make more sense to me.
With this acquisition, the HBO Max bundle, I suspect Videoland’s lead over Disney+ will widen again next year, despite Disney+’s efforts to grow reach with local partnerships with the likes of NPO or Max Verstappen.

